Featured
Data Insight
Jan. 2, 2026
Newsletter
Dec. 6, 2024
Data Insight
Jun. 19, 2024
AI development is concentrated in a handful of countries, with the United States and China far ahead of everyone else. Export controls, infrastructure investments, and geopolitics all shape who can build and deploy the most advanced systems. Epoch tracks which countries are leading in AI research and model development, how compute capacity breaks down geographically, and what this means for the global balance of AI capabilities.
Our open database of AI chip imports, using global customs and domestic production data to estimate the geographic distribution of AI chips.
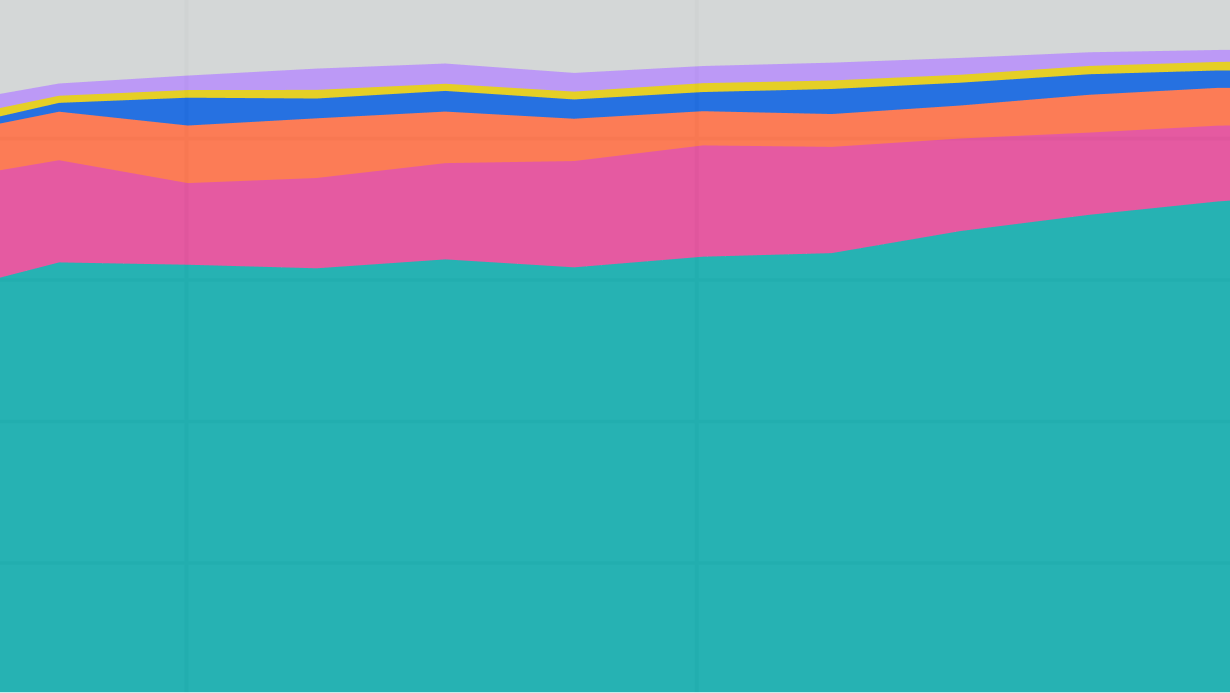
Our explorer uses customs records to estimate national shares. Since 2022, 72% of AI compute has ended up in the US and about 10% in China, including chips China makes itself.
China is 2.7× as exposed to semiconductor supply shocks as the US, Epoch AI estimates. Epoch traces chips through input-output tables to model the impact of a Taiwan shock and decoupling.
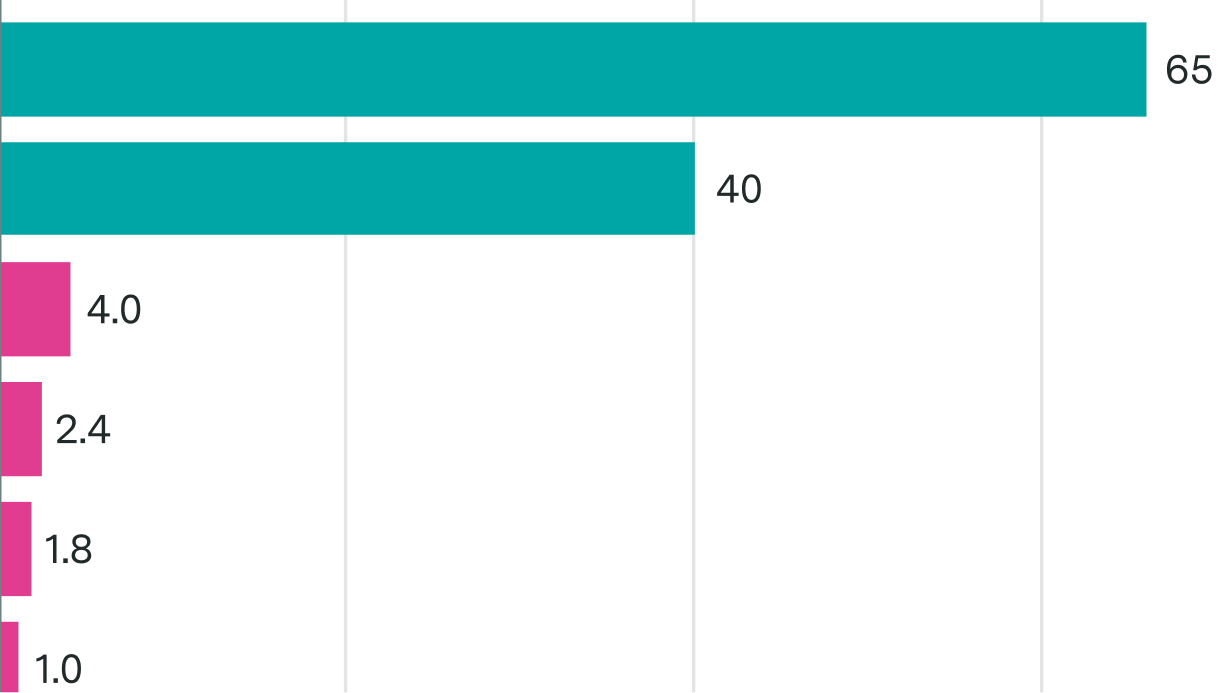
China's six leading AI firms earn about 10% of OpenAI and Anthropic's combined AI revenue. Epoch AI examines their five revenue streams: consumer apps, model access, enterprise and government solutions, licensing fees, and indirect monetization through cloud and advertising.
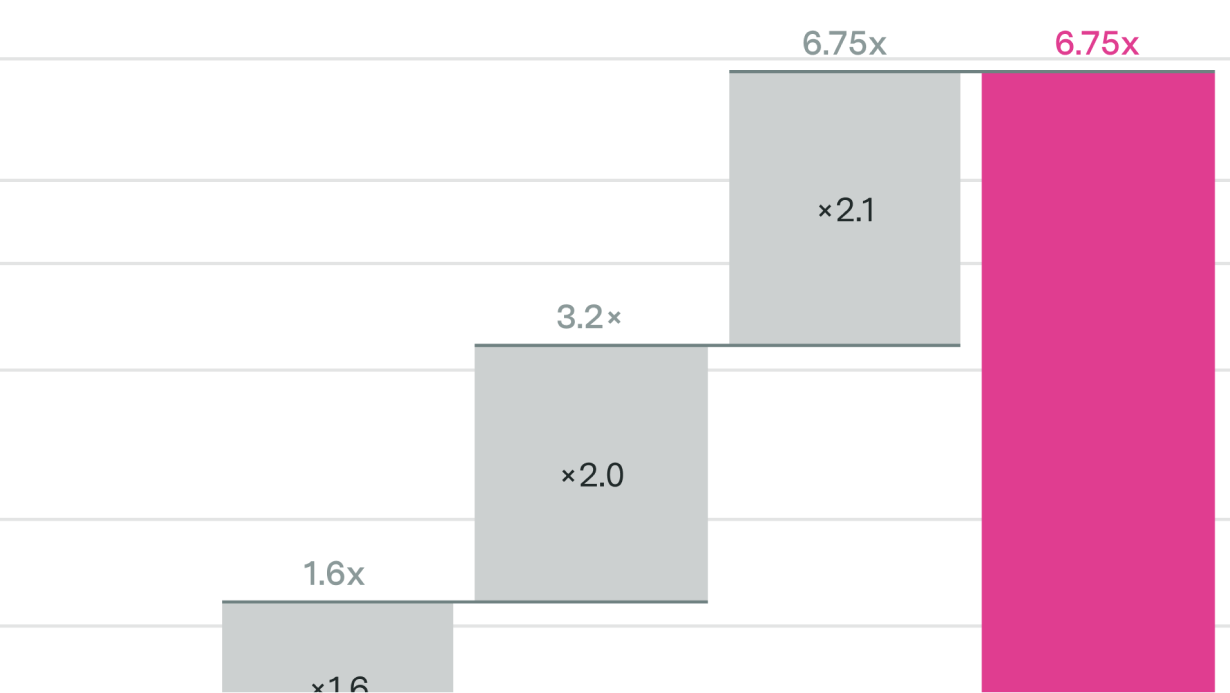
Huawei plans major gains in AI chip performance by 2030, but US export controls cap its most important scaling levers. Epoch AI estimates Huawei will produce less than 4% as much AI compute as Nvidia in 2026, a share that could be around 1% by 2028 without access to foreign memory.
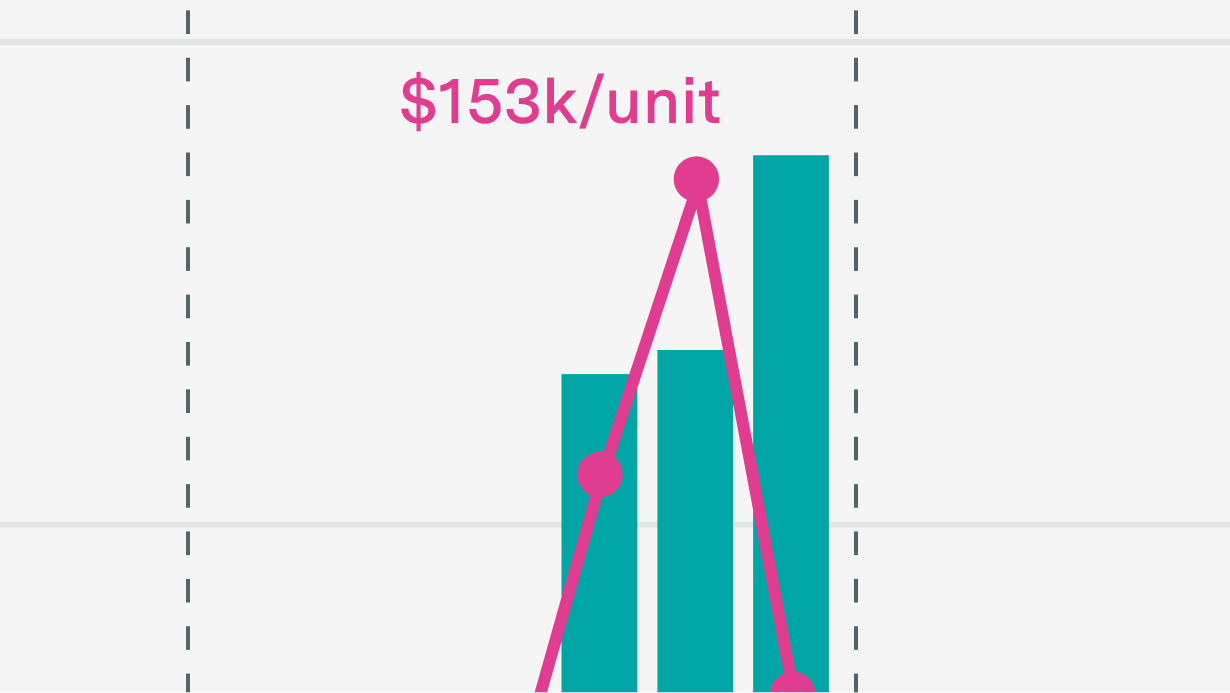
Epoch AI's analysis of trade data finds a pattern consistent with $3B worth of chips smuggled to China via Malaysia. China recorded $3.8B of server imports from Malaysia in 2024–25; Malaysia recorded only $0.6B of exports.
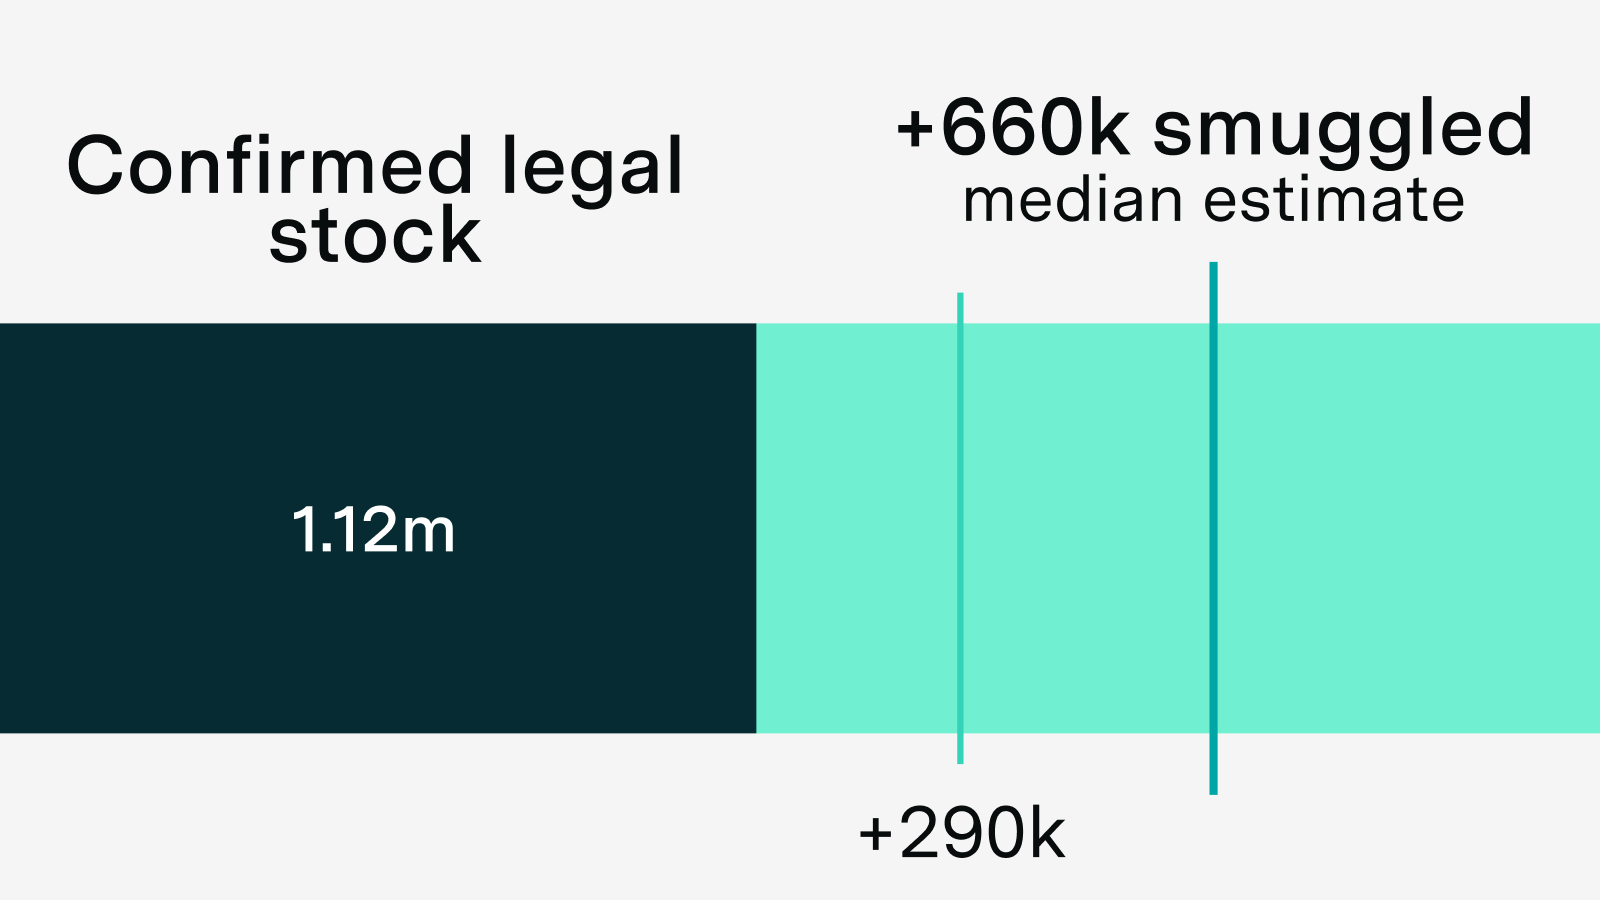
We estimate that between 290,000 and 1.6 million H100-equivalents (H100e) were smuggled to China through 2025. Our median estimate of 660,000 H100e would be roughly a third of China's total compute.
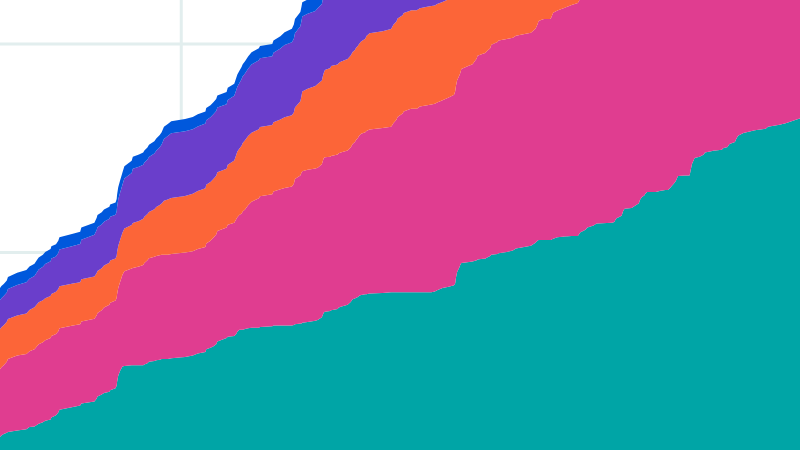
Amazon, Google, Meta, Microsoft, and Oracle collectively hold an estimated 71% of the world's cumulative AI compute as of Q4 2025, up from 63% in Q1 2024.
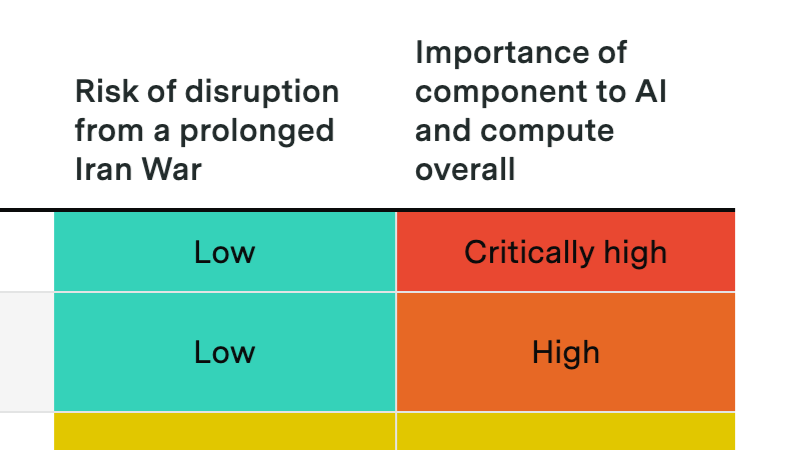
A prolonged Hormuz crisis probably won't derail the compute buildout, but it could slow data center expansion and disrupt Gulf investment flows into AI.
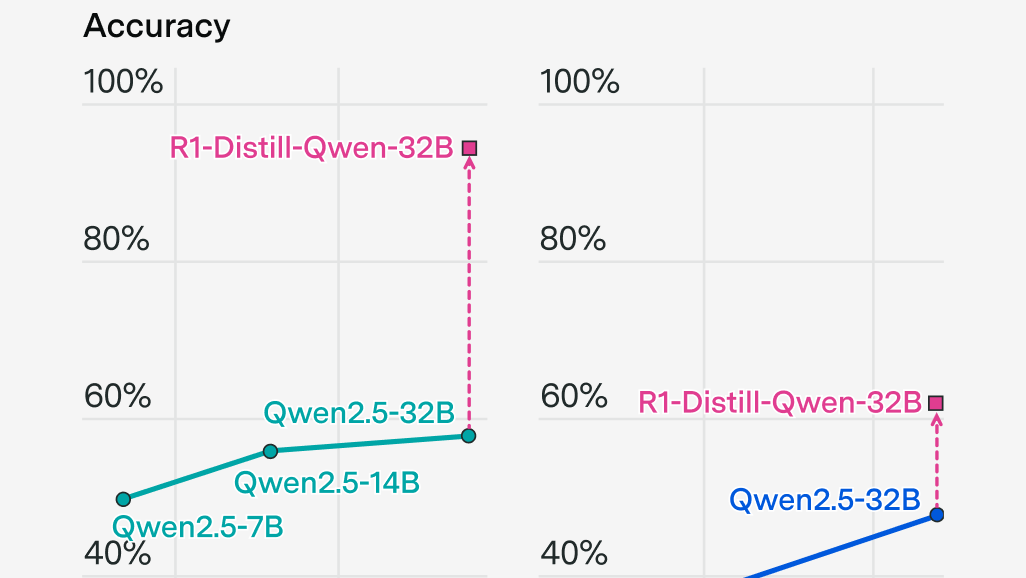
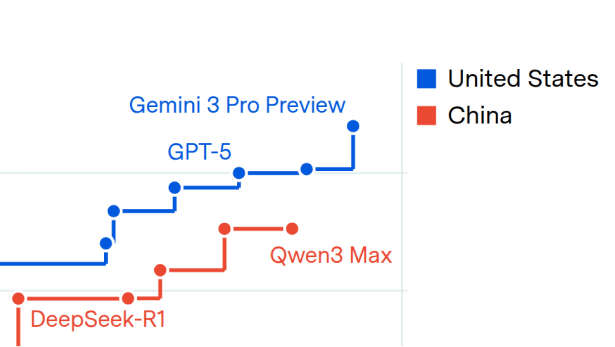
Can Chinese and open model companies compete with the frontier through e.g. distillation and talent?