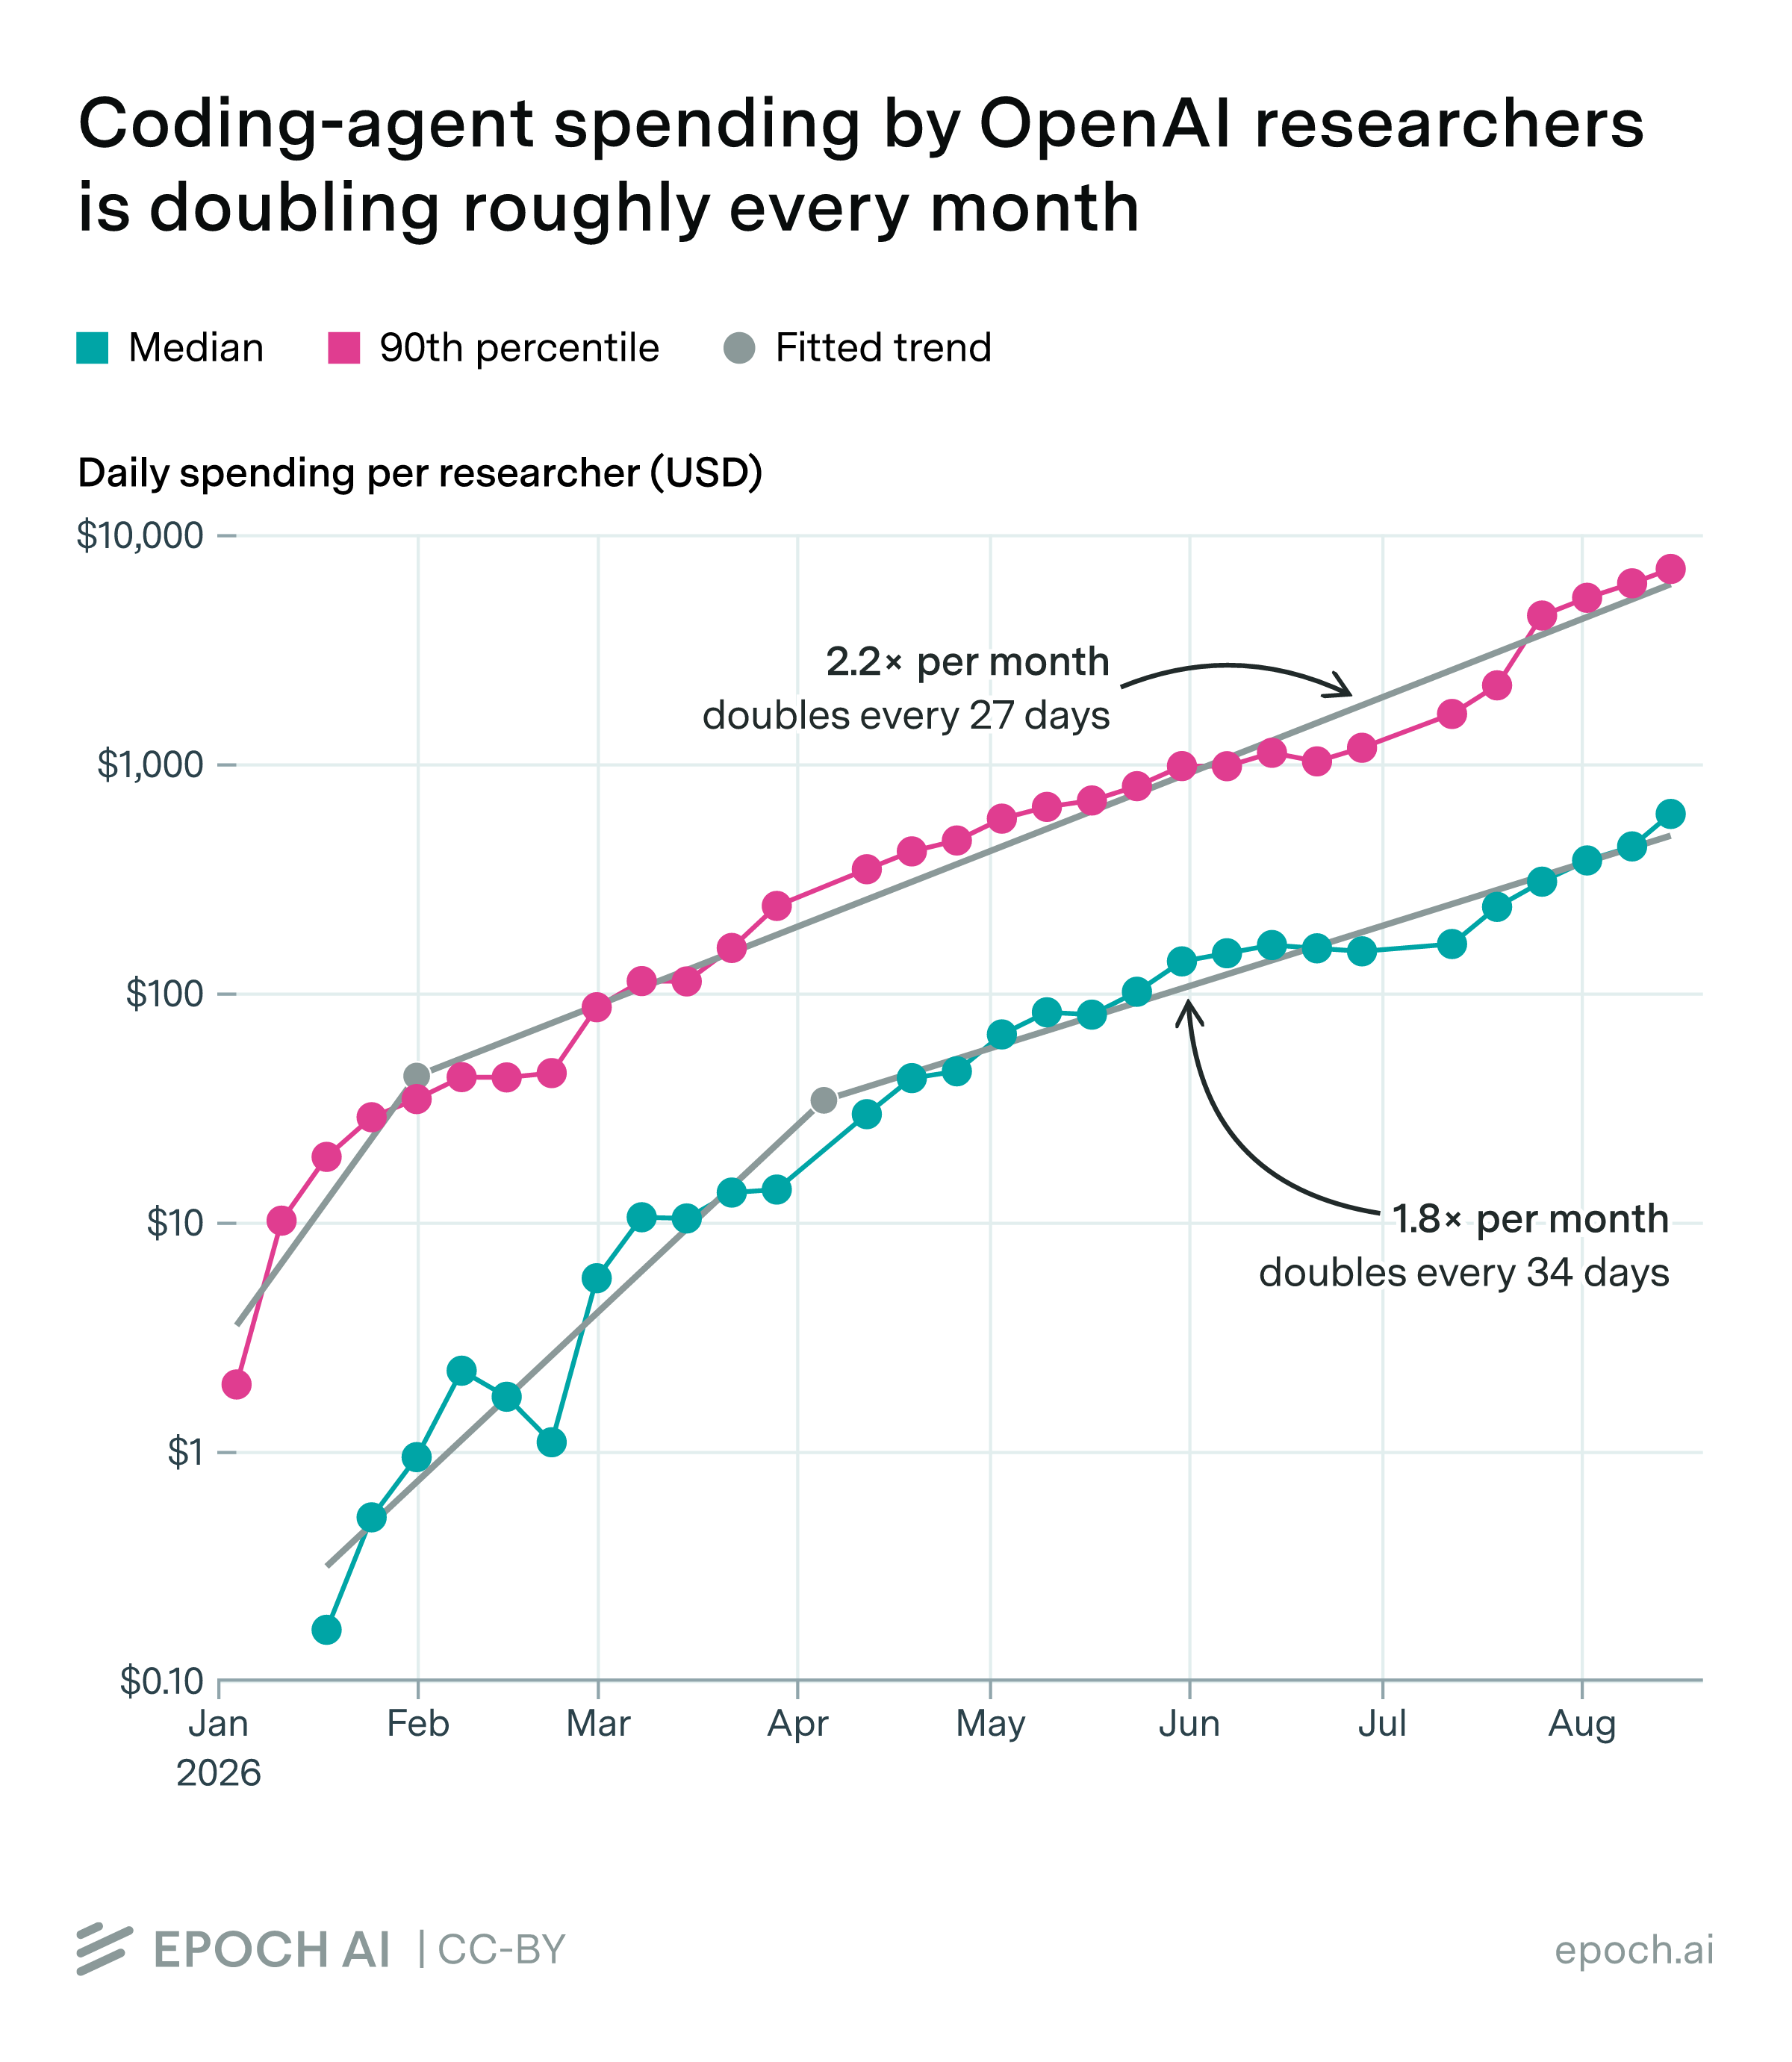
OpenAI researchers’ coding-agent usage, valued at API prices, has recently been doubling roughly every month, according to breakpoint fits.
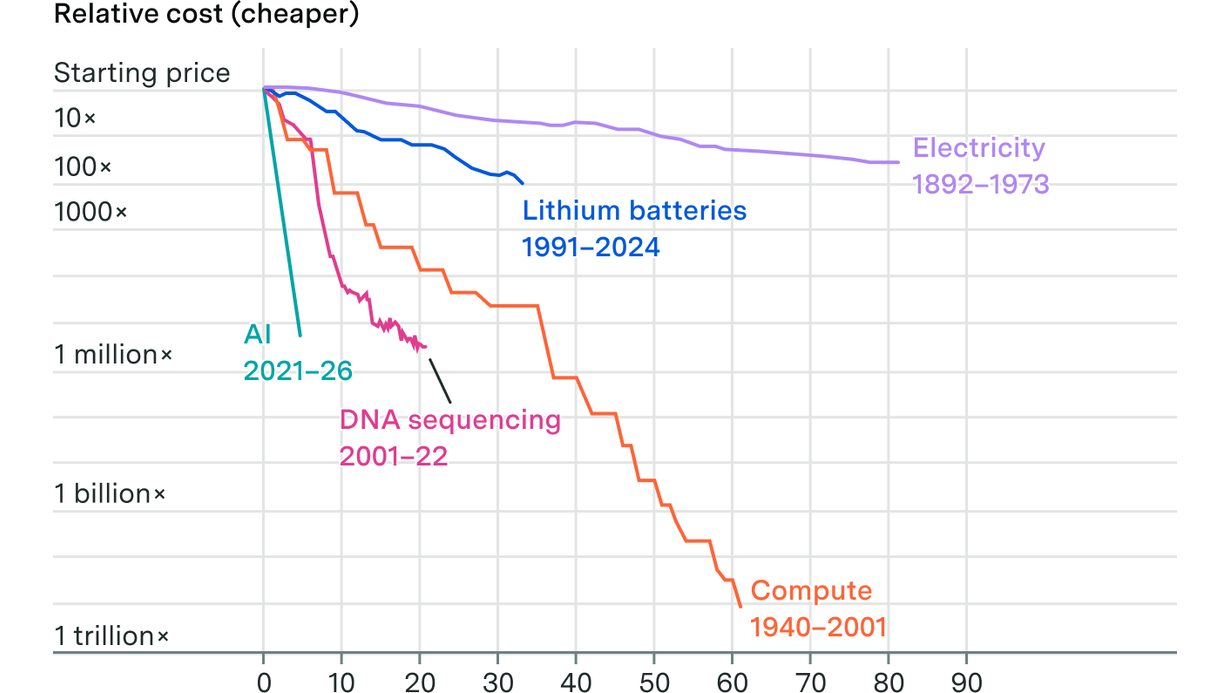
Epoch AI measures how fast the cost of a given level of AI performance is falling across five benchmarks covering math, science and games of skill: about 47% per quarter, or 13x per year, since 2023, faster than electricity, compute, batteries or DNA sequencing ever fell.
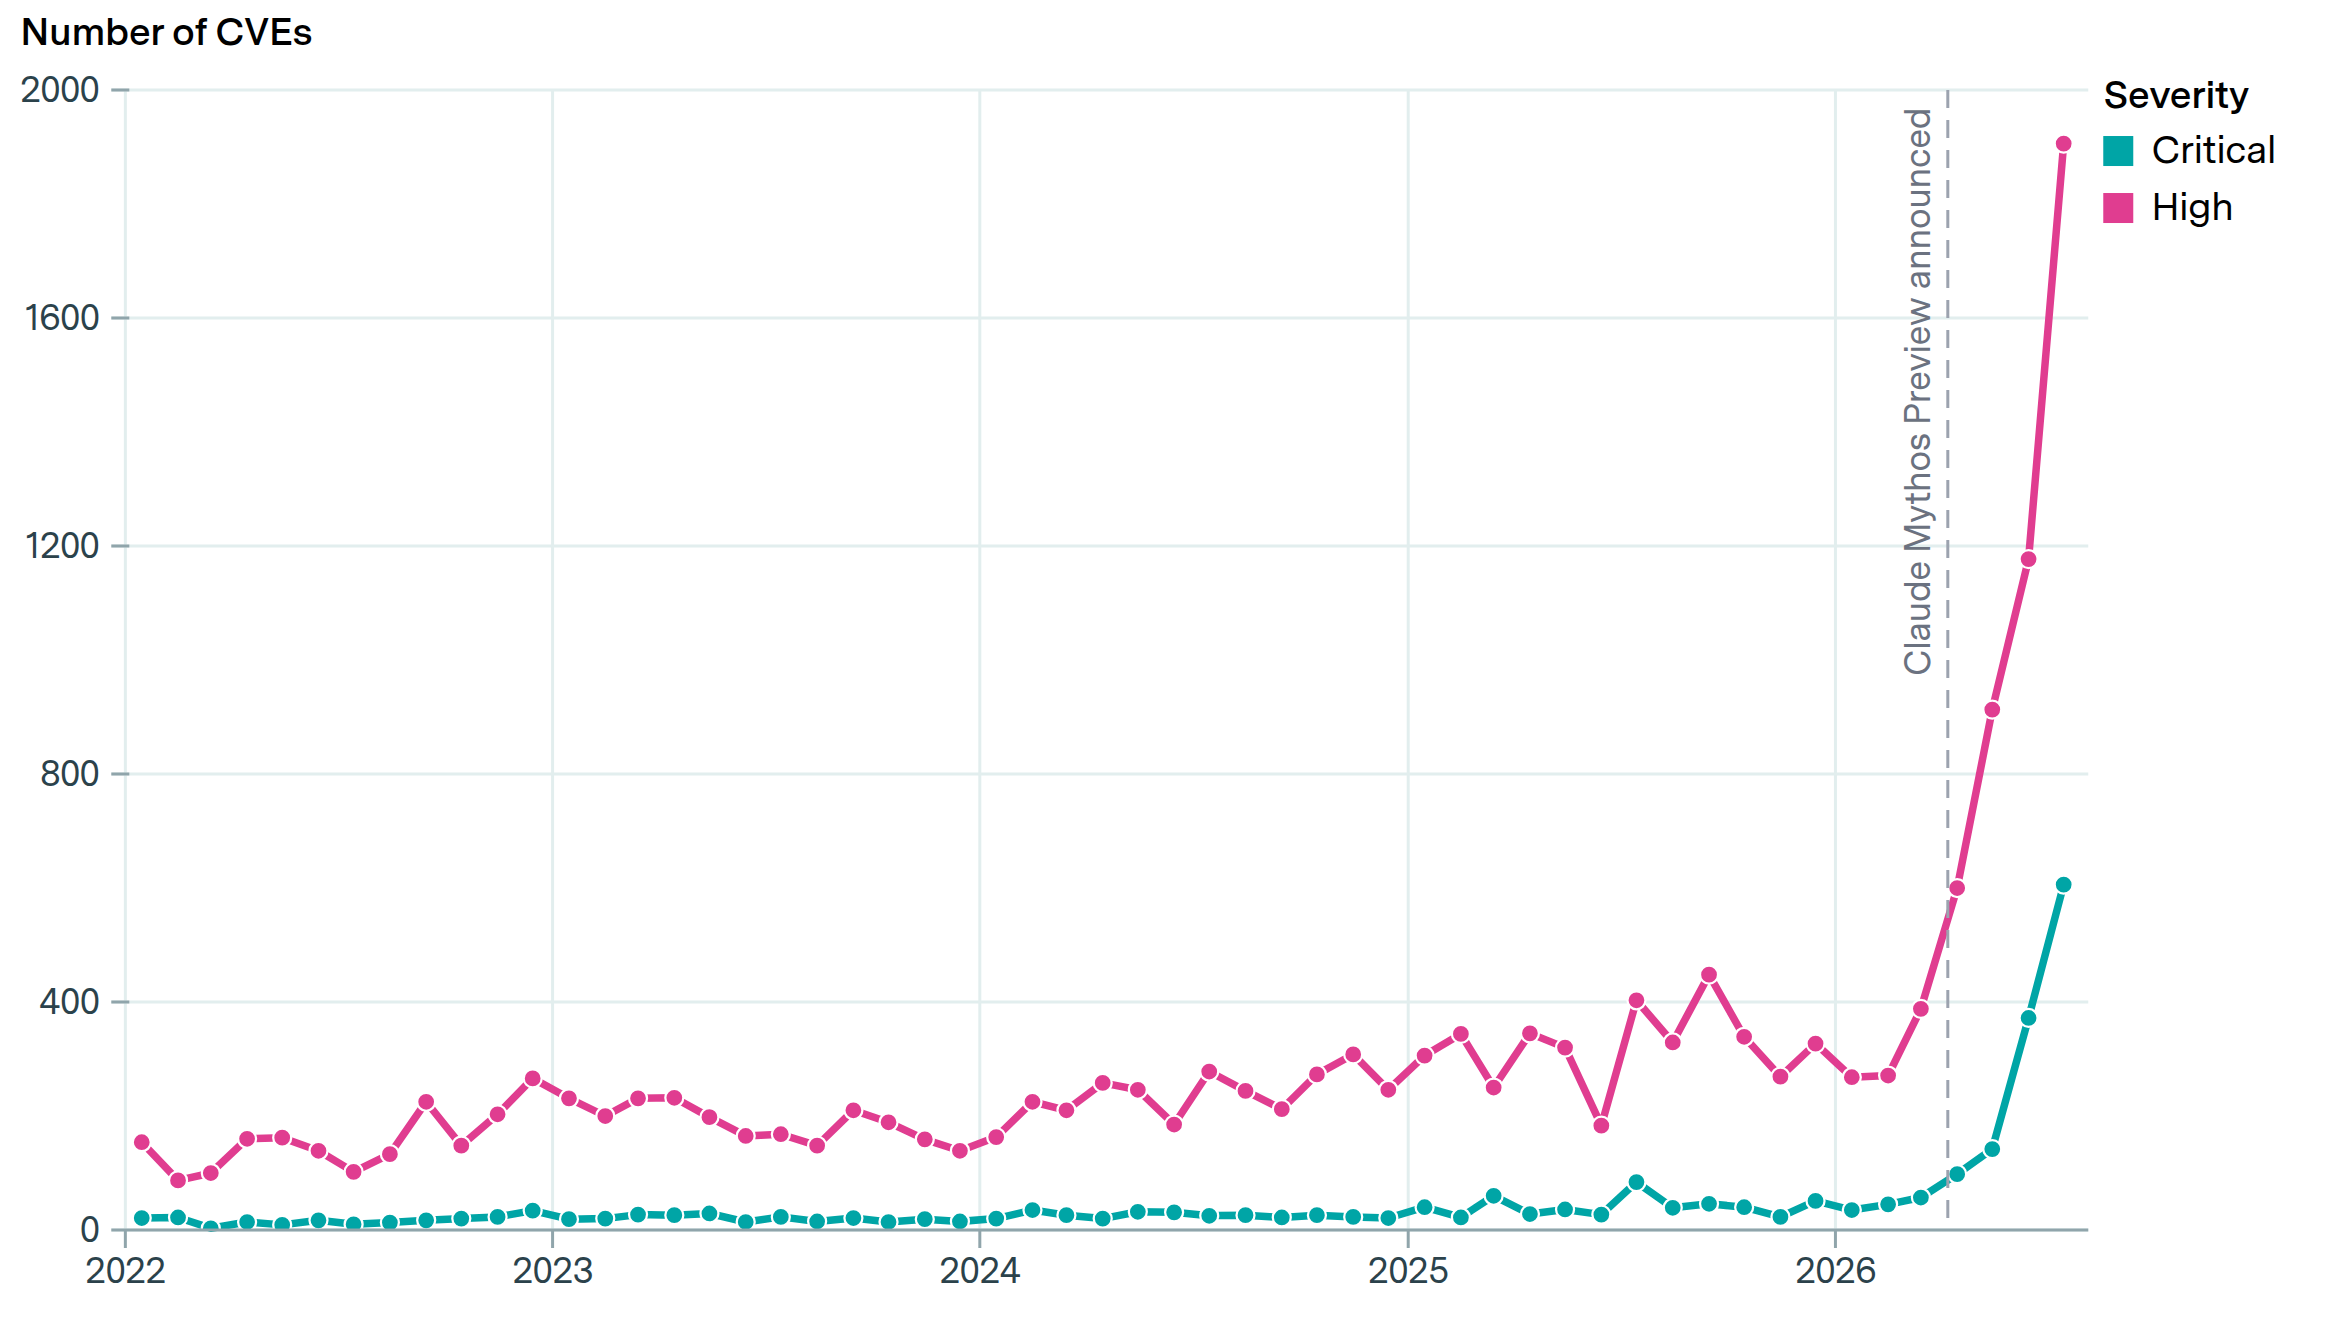
Notable organizations disclosed ~2,500 high- and critical-severity CVEs in July 2026, about 5× the pre-Mythos monthly record. Epoch AI's updated breakdown of vulnerability disclosures following Anthropic's Project Glasswing.
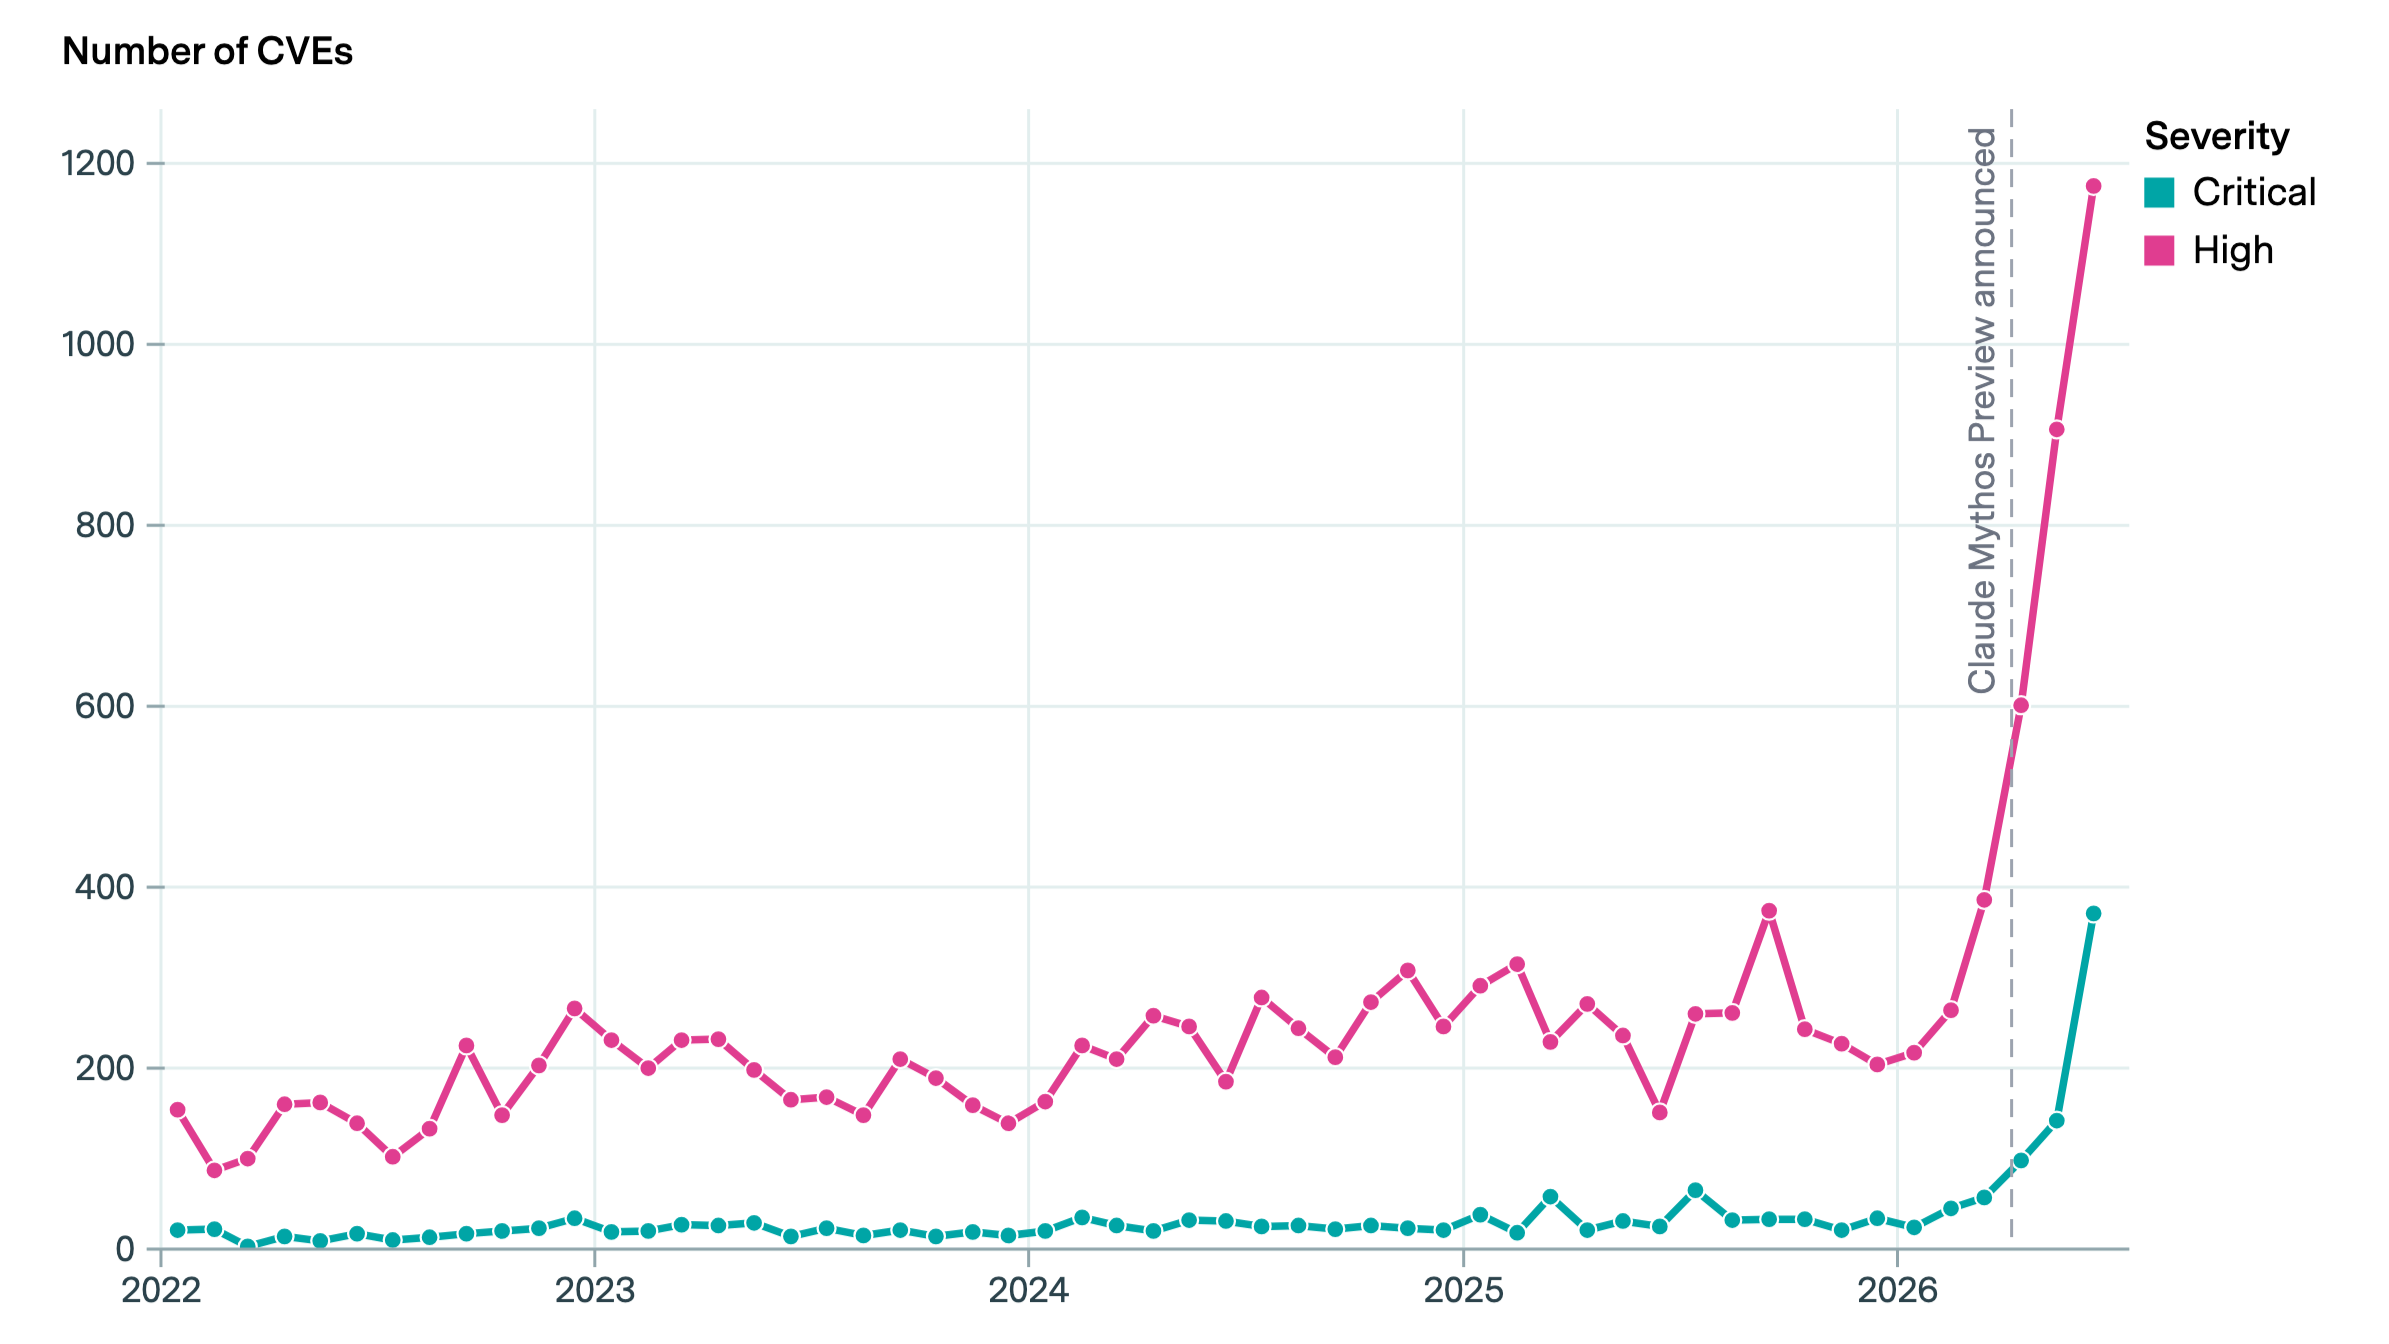
Notable organizations disclosed ~1,300 high- and critical-severity CVEs in June 2026, roughly 3.5× the pre-Mythos monthly record. Epoch AI's breakdown of vulnerability disclosures following Anthropic's Project Glasswing.
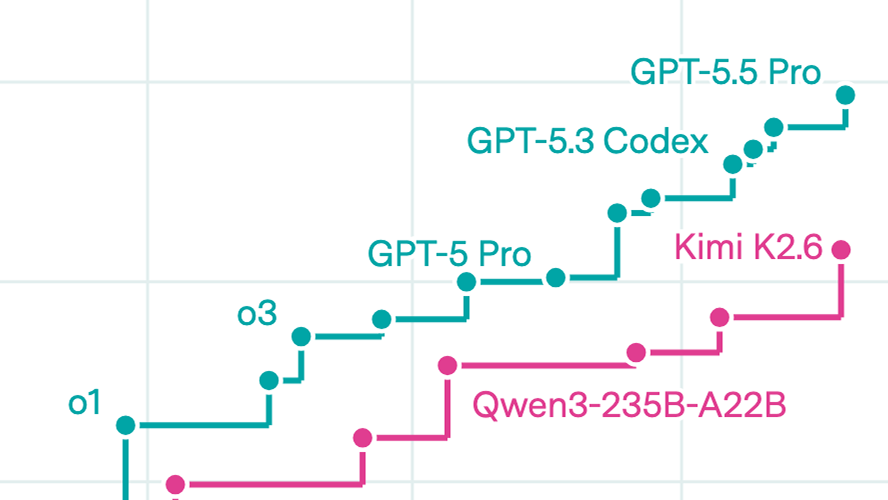
Since January 2026, the most capable open-weight models have lagged frontier closed models by an average of four months, or 8 ECI points.
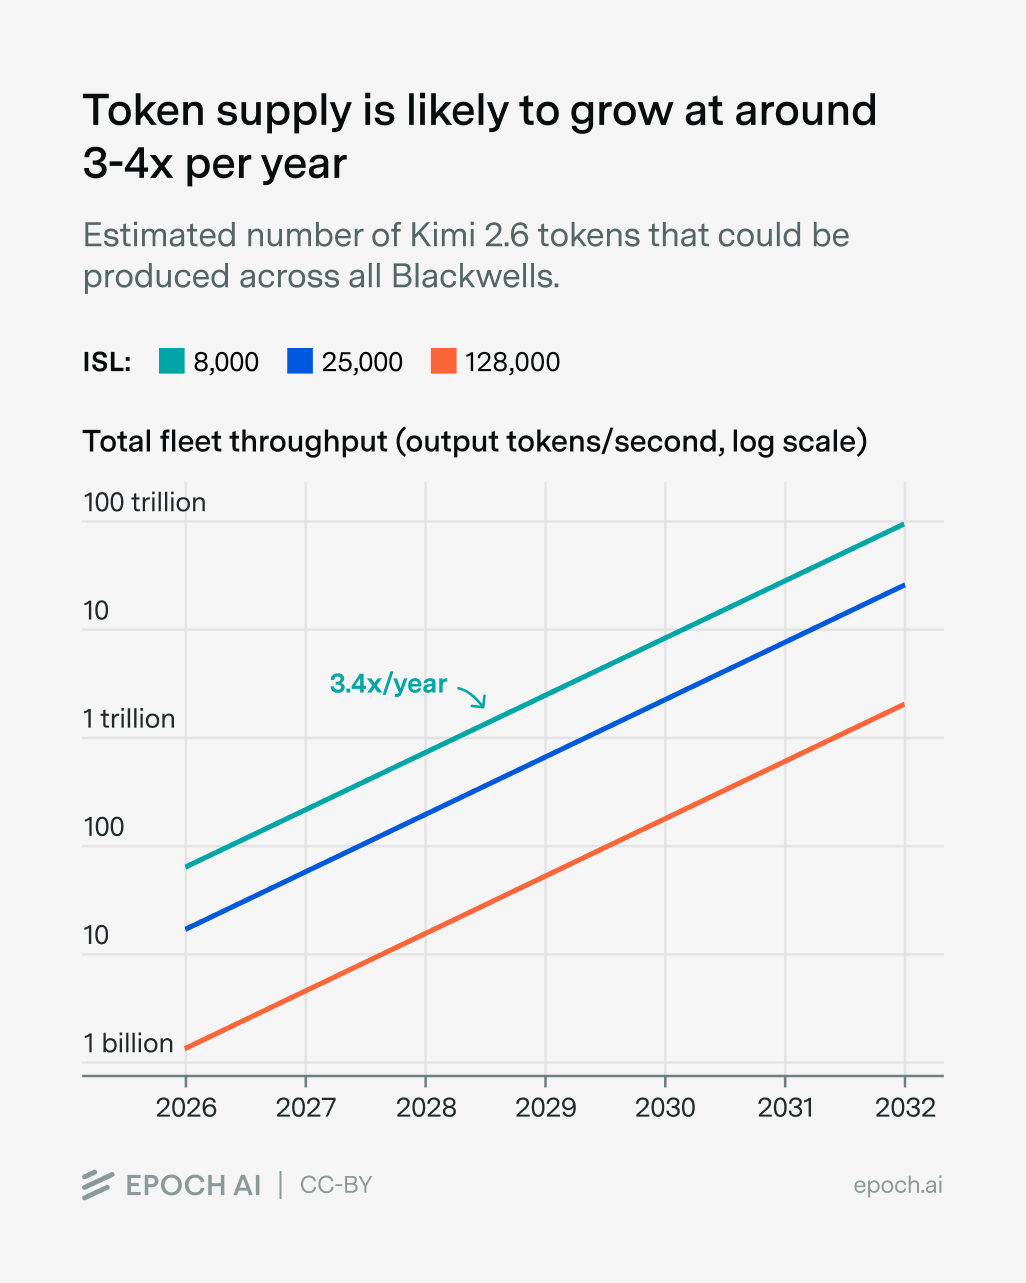
We estimated trends in global inference capacity and found that token demand appears to be growing much faster than supply.
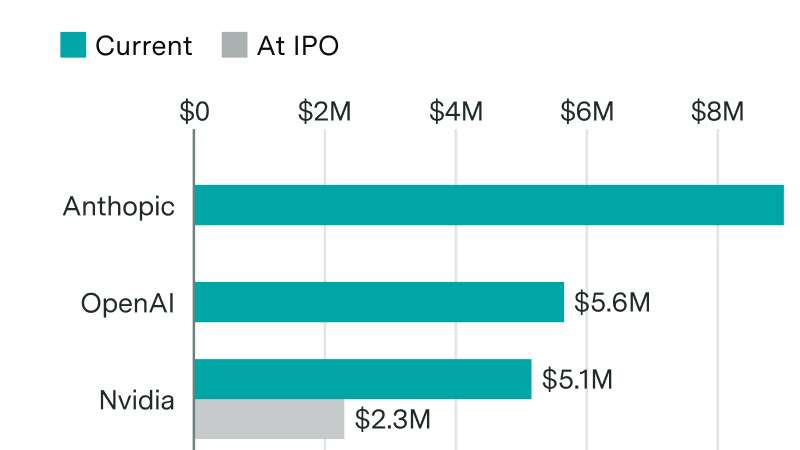
Anthropic and OpenAI generate roughly $14M and $6.5M in revenue per employee — higher than any other tech company in the Forbes Global 2000. Continued rapid growth in this metric at tens of billions in annualized revenue is unusual, and could reflect productivity gains from AI adoption.
Amazon, Google, Meta, Microsoft, and Oracle collectively hold an estimated 71% of the world's cumulative AI compute as of Q4 2025, up from 63% in Q1 2024.
We estimate Google is the largest single owner of AI compute, holding about one quarter of global cumulative capacity as of Q4 2025, primarily from its own custom TPU chips.
As of Q4 2025, memory bandwidth across global AI chips has reached roughly 70 million terabytes per second, enough to pass all data stored on the internet into memory in under an hour.